Retirement Isn’t Just a Financial Transition: How to Plan for Purpose, Not Just Money
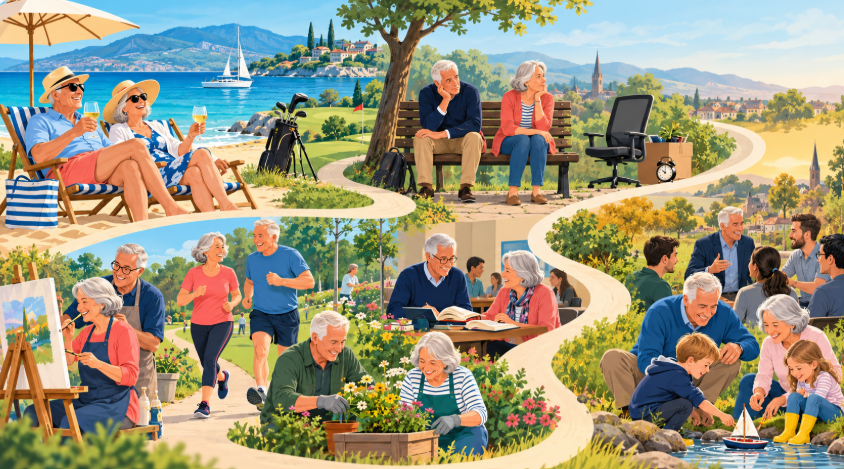
(image created by AI; article written by me)
By George Taylor, CFA
Published: 22/10/2026
Planning for the life, not just the pension
Retirement is as much a psychological transition as a financial one - yet most planning focuses almost entirely on making the money last. Dr Riley Moynes’s viral TED talk identifies four phases most retirees experience, from the initial honeymoon to a loss of identity and purpose.
According to the latest ONS life expectancy tables, a 65-year-old in the UK can expect to live for a further 19 years if male, or 21 years if female. For a couple, the chances that at least one of you is still going strong into your late 80s or beyond are higher still.
Most retirement planning, ours included, is focussed on making sure the money lasts that long.
But far less attention is paid to what you'll actually do with those two decades, and how you'll feel along the way.
This is the subject of a TED talk by Dr Riley Moynes, a Canadian former educator who went on to establish a wealth management firm. Despite being well prepared financially, Moynes found retirement harder than he'd anticipated. His talk, ‘How to squeeze all the juice out of retirement’, has since gone viral.
In it, he identifies four distinct phases that he believes most people experience during retirement, from the initial excitement of newfound freedom to the challenge of finding a renewed sense of purpose.
In this week's blog, I explore these four phases and how good financial planning can help you navigate them – not just making sure your money lasts, but helping you make the most of the years ahead.
1. The vacation phase
Phase one is the retirement most of us imagine whilst we're still working: travel, golf, long lunches and leisurely lie-ins. Freedom from the alarm clock!
It's also the version of retirement we're so often sold in the brochures: happy couples on yachts, strolling along sun-drenched beaches or walking hand in hand into the sunset. According to Moynes, this honeymoon period typically lasts one to two years.
From a financial planning perspective, this can be one of the most expensive periods of retirement. The bucket-list experiences, particularly long-haul travel, tend to be concentrated in the earlier, healthier years, when we have the energy and enthusiasm to enjoy them.
And that's something to plan for, rather than feel guilty about. In fact, we actively encourage clients to consider spending more in the earlier, more active years of retirement, rather than assuming they'll spend the same amount every year.
To help make this possible, we use cashflow modelling to explore how different spending patterns might affect a client's long-term financial position.
For those approaching or recently entering retirement, we go a step further, using stochastic modelling to test how their finances might hold up across a wide range of possible economic outcomes. Combined with a risk-based guardrails approach, this helps us establish an initial level of spending that has an estimated four-in-five chance of being sustainable over the course of retirement, based on our modelling assumptions. Crucially, we can also factor in the likelihood that spending will naturally ease in later years, rather than assuming it remains constant throughout.
The aim isn't simply to make the money last. It's to give clients the confidence to enjoy their retirement while they're fit and able, with a plan that can adapt as life unfolds.
2. The loss phase
Phase two is perhaps the most difficult, and certainly the one we're least likely to see featured in those glossy retirement brochures.
Moynes identifies five significant losses that can come with leaving work:
Your daily routine
Your sense of identity
Your workplace relationships
Your sense of purpose
For some, a degree of power or status
It's easy to underestimate just how much work provides beyond a salary.
One of our retired clients recently shared an observation. What she misses most about working isn't the job itself, but the regular interaction with younger people. The workplace naturally brought her into contact with different generations, perspectives and personalities – something that's not always so easy to replicate in retirement.
The important point is that experiencing this sense of loss doesn't mean you're failing at retirement. It's a perfectly natural response to a significant life transition. Moynes suggests that only a minority of retirees avoid this phase altogether, often because they've given considerable thought beforehand to what life after work might look like.
Ultimately, though, the real challenge isn't experiencing this phase. It's finding a way through it. Because while some people move on relatively quickly, others can remain stuck in this sense of loss for years.
And that's where Moynes's next phase becomes particularly important.
3. Trial and error
Moynes describes phase three as the point where you recognise that something needs to change. Having experienced the initial excitement of retirement, followed perhaps by a sense of loss, you begin asking a different question: What will give my life meaning and purpose now?
This is where the experimentation begins.
It might involve volunteering, part-time work, consultancy, studying something new or taking up a hobby you've always fancied trying.
Not everything will work out, and that's rather the point. Moynes emphasises that finding out what you don't enjoy can be just as valuable as discovering what you do.
The 'blowout year'
We often talk to clients about having a 'blowout year' early in retirement. In many ways, it's phase three done on purpose.
Rather than waiting for boredom or a lack of direction to set in, the idea is to set aside a year (or whatever period suits you) to try as many new things as you reasonably can, paying attention to what you enjoy and what you'd rather not repeat.
That might mean finally signing up for the college or university course you've been putting off for years, volunteering with a few different charities, trying some part-time or consultancy work, helping out more with family, getting into better shape (perhaps with the help of a personal trainer), or spending a month somewhere you've always wanted to live rather than simply visit.
And it doesn't all have to involve spending money. Some of the most rewarding experiences might cost very little.
The reflection is just as important as the activities themselves.
At the risk of sounding a bit ‘Kumbaya’, we’ve encouraged some clients to keep a journal during this phase.
It doesn't need to be anything elaborate. Just a few lines after each new experience, considering:
What you enjoyed, and what felt more like a chore.
Whether it gave you energy or left you feeling drained.
Who you spent time with, and whether that was part of the enjoyment.
Whether you'd genuinely want to do it again.
Over time, patterns should start to emerge. You might discover that it's not so much golf you enjoy, but the people you play with. Or that volunteering gives you a sense of purpose you hadn't realised you were missing.
By the end of your 'blowout year', the aim isn't necessarily to have found one great passion. It's to have a much clearer understanding of what makes retirement enjoyable and meaningful for you.
And that provides the starting point for the fourth and final phase.
4. Reinvention
Phase four is where Moynes believes retirees really find their stride.
Having worked through the earlier phases, the focus shifts towards some bigger questions: What gives my life meaning? What do I want to contribute? And what do I want this next chapter to look like?
According to Moynes, the answer almost always involves doing something for others, whether that's volunteering, mentoring, charity work or spending more time supporting family.
In many ways, this phase restores what may have been lost in phase two: a sense of purpose, meaningful relationships, routine and the feeling that you're making a difference.
Not everyone reaches this stage. Moynes’ research suggests that only a little over half of retirees make it through to phase four. But those who do are, in his experience, among the happiest people he's met.
Of course, what reinvention looks like will be different for everyone.
For some, it means returning to work, but on their own terms this time. That might involve taking on a non-executive role, doing a couple of days' consultancy each week, or trying something completely different from their previous career.
For others, reinvention might mean becoming more involved in family life, perhaps looking after the grandchildren a couple of days a week. Plenty of grandparents will tell you it's the most rewarding (and exhausting) job they've had.
Others might find that sense of purpose through volunteering, mentoring younger people, getting involved in their local community or supporting a cause that's important to them.
None of these is a step backwards, nor is there any single right way to approach retirement.
The common thread is finding something that matters to you, gives you a sense of purpose and, perhaps most importantly, makes you look forward to getting up in the morning.
Where financial planning fits in
If retirement involves different phases, your financial plan needs to be dynamic, evolving as your life and priorities change.
Your objectives and spending patterns will naturally shift over time. In the early years, the focus might be on funding bucket-list holidays and experiences. Further down the line, it could be about helping children or grandchildren financially, or simply enjoying a quieter pace of life.
Your financial plan needs to evolve with you, rather than being built around a fixed set of assumptions made when you first retire.
That's where good financial planning, and particularly cashflow modelling, comes in.
First, it's about giving you the confidence to spend.
We use cashflow modelling to explore how your spending might change throughout retirement, from the travel and experiences of the early years to a 'blowout year' of trying new things, followed by potentially lower spending later on.
We also test your plan against a wide range of possible investment outcomes, rather than relying on a single assumed rate of return. Regular reviews and spending guardrails help us identify when there's scope to spend more and when some restraint might be needed.
For many clients, the biggest benefit is simply having the confidence to book that trip or pursue that ambition without constantly worrying whether they can afford it.
Second, it's about making your retirement income work for you.
That includes drawing on pensions, ISAs and other investments tax-efficiently, but also considering how you receive your income.
For example, arranging a regular monthly payment from your investments, much like the salary you're used to, can make the transition from saving to spending feel more comfortable.
Third, and perhaps most importantly, it's about accountability.
Financial planning isn't just about the numbers. It's also about making sure the things you said you wanted to do actually happen.
If you told us you wanted to spend a month in Italy, get fitter or finally take that course, and twelve months later you haven't, we'll ask why.
Sometimes priorities change, and that's absolutely fine. But if the reason is that you're worried about spending the money, that's exactly the sort of concern your financial plan should help address.
Final thoughts
Moynes's four phases are a useful reminder that retirement is as much a psychological transition as a financial one.
It's worth thinking not just about what you're retiring from, but what you're retiring to.
And perhaps that's the real value of a 'blowout year': giving yourself the time and freedom to try new things, discover what you enjoy and work out what you want the next chapter to look like.
If you haven't watched Moynes's TED talk, I'd recommend it. You can find it here.
And if you'd like to talk about your own retirement plans, please do get in touch.
Happy Thursday.
Kind regards,
George
Referrals Welcome
Our business grows mainly through personal recommendations. If you know someone—whether a friend, family member or colleague—who might benefit from financial planning, we’d be grateful if you could share my details with them. Alternatively, you can pass their details on to me, and I’ll be happy to reach out.
Regulatory Information
Blincoe Financial Planning Limited is an appointed representative of Sense Network Ltd, which is authorised and regulated by the Financial Conduct Authority. Registered in England & Wales (No. 14569306). Registered Office: Star Lodge, Montpellier Drive, Cheltenham, GL50 1TY.
Important Disclaimer
This blog is for general information only and is intended for retail clients. It does not constitute financial or tax advice, nor is it an offer to buy or sell any specific investment. Since I don’t know your personal financial situation, you should not rely on this content as tailored advice. While we aim to provide accurate and up-to-date information, we cannot guarantee that all details remain correct over time. We are not responsible for any losses resulting from actions taken based on this blog’s content.
Start here
Wondering if we'd be a good fit?
Answer a few short questions about your situation. If it looks like we can help, you can book an introductory call with one of our planners at the end.
See if we're a good fitTwo minutes. No obligation.