How Much Will You Spend in Retirement? Why the 'Retirement Smile' Makes Your Number Lower Than You Think
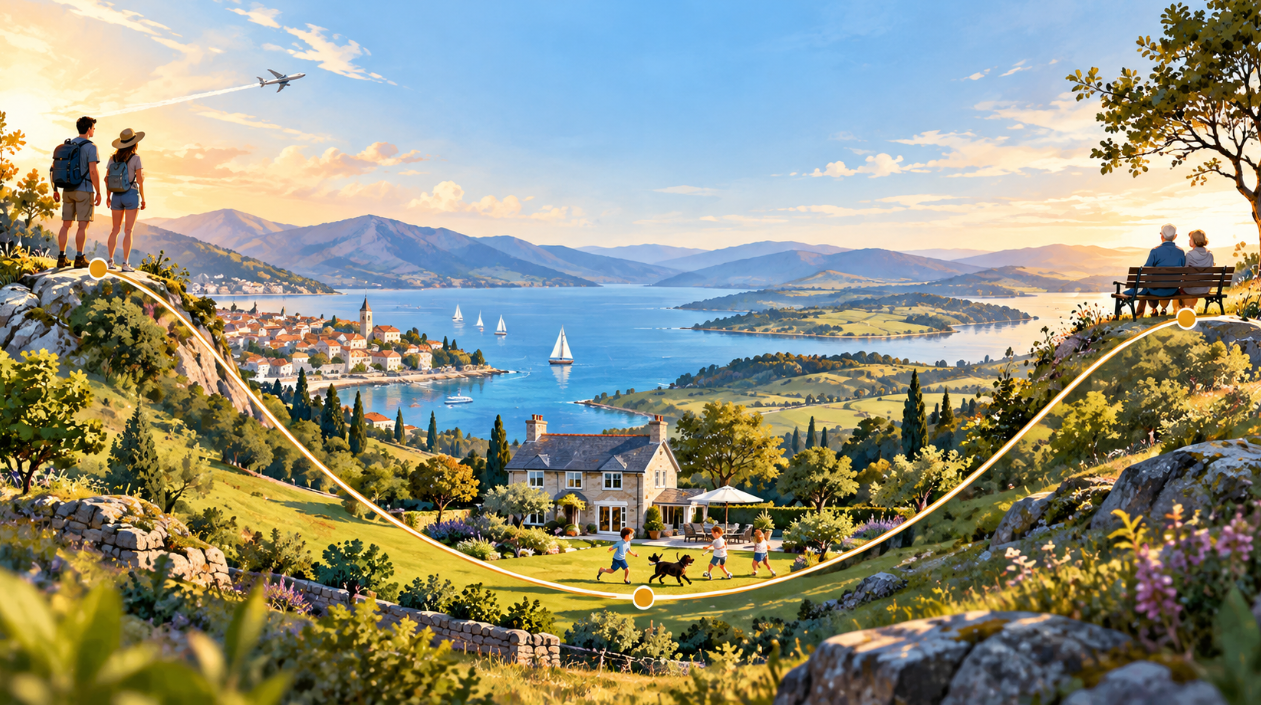
(image created by AI; article written by me)
By George Taylor, CFA
Published: 24/09/2026
Why spending rarely stays flat throughout retirement
Most retirement models assume spending rises with inflation every year, but research by David Blanchett shows real retirement spending falls by around 1% annually on average. For a retiree targeting £72,000 a year, accounting for this 'retirement smile' reduces the pot needed at 65 by roughly £200,000 - enough to retire years earlier or spend £900 more every month in the ‘go-go’ years.
What does the good life actually look like in retirement – and does it look the same at 66 as it does at 86?
Retirement planning is probably the most common reason people seek financial advice.
When can I afford to retire? Should I stop completely, or wind down gradually? How much can I afford to spend? And, more broadly, am I going to be OK?
Regular readers will know that cashflow modelling is the key tool here. We take your current financial position, layer in assumptions for things like inflation and future investment returns, and project how your finances might evolve over the rest of your life.
But the most important assumption in that analysis is spending.
What are you spending today? What might you spend once you stop working? What about the bigger, aspirational goals – the holidays, cars, home improvements, helping the children or grandchildren – and what might those cost?
Arriving at an initial retirement spending target therefore requires some work. There’s the relatively mundane exercise of budgeting, but also the much more enjoyable job of thinking about what you actually want your retirement to look like.
And even once you’ve arrived at that number, there’s another consideration: your spending is unlikely to stay the same throughout retirement.
That might sound obvious. Yet the starting point for many retirement models – particularly DIY calculators and simple rules of thumb such as the 4% ‘safe withdrawal rate’ – is effectively that spending rises with inflation every year.
In reality, that’s rarely the case.
For most retirees, spending starts relatively high during the early, active years of retirement. It then gradually tails off as people get older, before potentially increasing again in later life as health and care costs become more significant.
Plot that spending over the course of retirement and you get something resembling a smile.
Go-go, slow-go, no-go
One way of thinking about why spending changes comes from American financial planner Michael Stein, who famously divided retirement into the ‘go-go’, ‘slow-go’ and ‘no-go’ years.
The terminology is a little blunt, but the underlying idea is useful.
The ‘go-go’ years are the early years of retirement. Work is no longer taking up five days a week, but for many people their health, energy and appetite for new experiences remain much the same. Suddenly, there is more time for the long-haul holidays, weekends away, hobbies, projects, golf, eating out and all the other things work previously had a habit of getting in the way of.
As the years pass, the pace often slows. Not necessarily because life becomes less enjoyable, but because what people want to do with their time changes. There may be fewer big holidays, less driving and eating out, and more time spent closer to home. With that, discretionary spending often falls too.
Later still, the mix of spending can change again. Lifestyle spending may be lower, while health, support and potentially care become more important.
Of course, nobody moves neatly from one phase to another at a particular age. Some people are travelling the world well into their 80s; others prefer a quieter retirement from day one.
But Stein’s framework captures an important point: retirement isn't one 30-year-long lifestyle, so why would we expect it to have one constant level of spending?
What does the data tell us?
American researcher David Blanchett’s widely cited work, Exploring the Retirement Consumption Puzzle, found that, after allowing for inflation, retirement spending tends to fall by around 1% a year on average, with the decline becoming more pronounced during the middle years of retirement.
Of course, there are exceptions to this. Other research has found some wealthier retirees actually spend more as they age, particularly where pension and investment income grows faster than their expenditure.
But the broader evidence points in the same direction: for many people, spending tends to fall in real terms as they move through retirement, before potentially rising again in later life.
The cost of ignoring the smile
If your plan assumes that today’s spending will continue, rising with inflation, for the rest of your life, you may overstate how much you actually need to sustain your retirement.
That can have a very real consequence. If the model tells you that you need a bigger pot, the natural response may be to retire later – or to spend more cautiously once you do.
The problem is that this caution is most likely to affect the early, active years of retirement. An unrealistic assumption about what you might need decades from now could leave you underspending today – when you are healthiest, most active and perhaps best placed to enjoy the money you have accumulated.
The aim isn't to spend more for the sake of it. It's to have the confidence to spend appropriately, at the right time, on the retirement you've spent your working life building towards.
A worked example
Take Helen, a hypothetical client retiring at 65 with a target spend of £6,000 a month, or £72,000 a year.
To keep things simple, we’ll ignore other sources of income, such as private and State Pensions, and assume a 3% real investment return after charges – say 6% nominal growth less 3% inflation. We’ll run the plan to age 100, as we do in our own retirement modelling.
Please note, when investing, your capital is at risk. The value of your investment (and any income from it) can go down as well as up, and you may get back less than you invested. Neither simulated nor actual past performance is a reliable indicator of future performance.
1. Flat spending
Under a flat-spending assumption, Helen’s £72,000 annual expenditure remains constant in real terms throughout retirement.
On those assumptions, she would need around £1.55 million at age 65 to fund her spending to age 100.
2. Declining spending
Now apply the retirement smile, with spending declining by around 1% a year in real terms.
Helen’s £72,000 starting expenditure gradually falls as she gets older. Reflect that decline in the calculation and the pot required at 65 falls to around £1.35 million.
That’s a difference of roughly £200,000, or 13%.
What does 13% actually mean?
Thirteen per cent might not sound like much. However, over a retirement lasting several decades, it can make a material difference.
For someone still building towards their retirement number, needing around £200,000 less could potentially bring financial independence forward by several years, depending on how much they are saving and how their investments perform.
That could mean stopping work earlier, moving to part-time hours sooner, or simply having greater confidence that the retirement they want is already affordable.
But consider the alternative.
Suppose Helen reaches 65 with the £1.55 million anyway. Rather than using that additional capacity to retire earlier, she could choose to spend more during the early years of retirement.
On exactly the same simplified assumptions, that pot could support initial spending of around £6,900 a month, in today’s terms, rather than £6,000, with spending then gradually declining by 1% a year in real terms.
That’s roughly £900 more every month, or almost £11,000 per year.
That could be the extra blowout holiday – perhaps two. More weekends away. Helping the family. Eating out more often. Or simply having the freedom to say yes more often during the years when Helen is most likely to want – and be able – to do those things.
So the same £200,000 difference can work in two directions: it could bring retirement forward, or it could support a materially higher standard of living during the early, active years of retirement.
What about the uptick at the end?
The upturn at the end of the smile understandably worries people. Later-life care costs can be significant and, more importantly, difficult to predict.
Rather than simply adding an arbitrary care allowance to everyone’s future spending, we tend to deal with that uncertainty as follows:
First, model over a long timeframe. We typically run retirement plans to age 100 – often 10 to 15 years beyond a typical life expectancy. That extra runway provides a meaningful buffer. In effect, by modelling for considerably more years than we would ordinarily expect the plan to be needed, we build additional capacity into the later years that can help absorb an increase in costs if health or care needs arise.
Second, consider property wealth as a later-life reserve. This is the approach most of our clients take. For those with significant equity in their home, we can think of the property as the ultimate insurance pot – an asset that may never need to be touched, but which provides an additional layer of security if a prolonged or particularly expensive care need arises later in life. In that scenario, downsizing or, where appropriate, equity release could provide additional capital to meet those costs.
Given how unpredictable later-life care can be – whether it will be needed at all, when it might arise, how long it might last and what it might cost – we generally prefer this combination of a longer planning horizon and a separate contingency to automatically building substantial care costs into every year of the plan.
Otherwise, there is a danger of solving for an uncertain future cost by unnecessarily restricting spending today: sacrificing the early, active years of retirement for fear of costs that may or may not arise much later.
Summary
Retirement spending isn't a straight line.
For many people, spending is higher during the early, active years, gradually falls as retirement progresses, and may eventually rise again as health and care become more important.
That matters because assuming today's spending simply rises with inflation forever can make retirement look more expensive than it may actually be. And the consequence isn't confined to a spreadsheet: an overstated retirement number can affect the decisions you make today.
You might work for longer than necessary. You might delay moving to part-time hours. Or you might reach retirement with enough money, but still hold back from the holidays, experiences and time with family that you spent decades working towards.
Later-life costs still need to be considered, of course. That might mean modelling over a longer timeframe, retaining property wealth as the ultimate contingency for prolonged care needs, or building in other safeguards appropriate to your circumstances.
But the objective isn't to spend as much as possible, nor is it to preserve as much as possible.
It's to have the confidence to spend the right amount, at the right time, on the retirement you actually want.
Happy Thursday.
Kind regards,
George
Referrals Welcome
Our business grows mainly through personal recommendations. If you know someone—whether a friend, family member or colleague—who might benefit from financial planning, we’d be grateful if you could share my details with them. Alternatively, you can pass their details on to me, and I’ll be happy to reach out.
Regulatory Information
Blincoe Financial Planning Limited is an appointed representative of Sense Network Ltd, which is authorised and regulated by the Financial Conduct Authority. Registered in England & Wales (No. 14569306). Registered Office: Star Lodge, Montpellier Drive, Cheltenham, GL50 1TY.
Important Disclaimer
This blog is for general information only and is intended for retail clients. It does not constitute financial or tax advice, nor is it an offer to buy or sell any specific investment. Since I don’t know your personal financial situation, you should not rely on this content as tailored advice. While we aim to provide accurate and up-to-date information, we cannot guarantee that all details remain correct over time. We are not responsible for any losses resulting from actions taken based on this blog’s content.
Start here
Wondering if we'd be a good fit?
Answer a few short questions about your situation. If it looks like we can help, you can book an introductory call with one of our planners at the end.
See if we're a good fitTwo minutes. No obligation.